 If you own an asset, either real property or otherwise, you may have heard the term “step-up in basis.” It may sound like complicated tax terminology, but the basic concept is relatively simple.
For real estate owners who have held property for many years, understanding basis can be an important part of deciding what to do with that property and planning for the future.
What Is “Basis”?
In simple terms, basis is your tax starting point in a property.
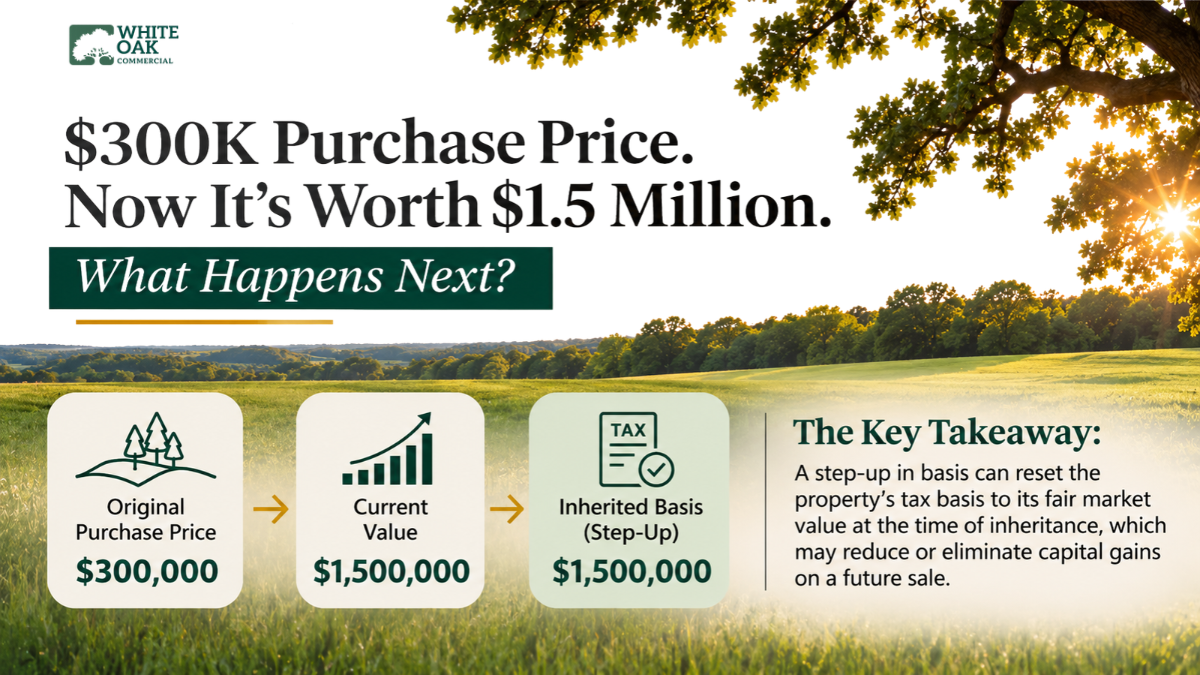
Let’s say you purchased a piece of land 20 years ago for $300,000.
Today, that same property is worth $1.5 million.
That’s a significant appreciation in value, and is a scenario to which many longtime property owners in the Triangle can relate. Land that was once on the edge of town may now be surrounded by development as roads, utilities, housing and businesses move into the area.
When a property is sold, the taxable gain is generally based on the difference between the sale price and the property’s adjusted basis. Your adjusted basis may differ from your original purchase price because of improvements, depreciation and other adjustments.
So What Is a “Step-Up”?
Generally, when someone inherits property, the tax basis is adjusted to the property’s fair market value as of the previous owner’s date of death, subject to certain rules and exceptions. This is commonly referred to as a step-up in basis.
Let’s go back to our example:
Original purchase price: $300,000
Value at owner’s death: $1.5 million
If the general rule applies, the heir’s basis would be approximately $1.5 million, rather than the original $300,000.
Now imagine the heir sells the property shortly afterward for $1.5 million.
Because the basis was adjusted to the property’s value at the time of inheritance, there may be little or no capital gain attributable to the appreciation that occurred during the original owner’s lifetime.
That’s the significance of the step-up in basis.
What About Depreciation?
For commercial property owners, depreciation is another important consideration.
If you’ve owned a commercial building for many years, you may have claimed depreciation deductions along the way. Those deductions can reduce your adjusted tax basis, which may increase the taxable gain when you eventually sell.
Land is different. Land itself generally isn’t depreciable, although buildings and certain improvements may be.
This is another reason why knowing your adjusted basis, not just what you originally paid, matters when evaluating a potential sale or transfer.
Does Every Inherited Property Get a Step-Up?
Not necessarily.
The tax treatment depends on how the property is owned and how it is transferred. Inherited property is generally treated differently from property gifted during someone’s lifetime, and special rules can apply to trusts, jointly owned property, business entities and other ownership arrangements.
Before making decisions based on a potential step-up in basis, property owners should consult with their CPA, tax advisor or estate-planning attorney.
How Can We Help?
Commercial real estate, particularly land, is often held for decades. A family farm or investment property purchased years ago may now sit along a major growth corridor and be worth several times what the family originally paid.
For many families, real estate represents more than an investment. It’s part of their financial legacy and something they hope to pass along to future generations. Deciding when to buy, hold or sell can have a lasting impact on that legacy.
At White Oak Commercial, we understand that selling a property, particularly one that has been in a family for generations, is not a decision to take lightly. Our role isn’t to convince you to sell. It’s to help you understand your options, evaluate the market and determine when the timing and strategy make the most sense.
Whether you’re considering selling today, holding for another five years or planning for the next generation, we want to help you make an informed decision that supports your long-term goals.
For questions about your individual tax situation or estate plan, consult your CPA, tax advisor or estate-planning attorney.